Why Mubadala is Placing Its Trust in Luckin Coffee, Despite Its Past Accounting Scandal
Mubadala Is Betting on China’s Coffee Market After Luckin’s Accounting Scandal
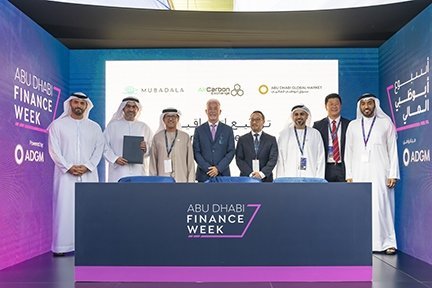
Mubadala Investment is making a significant minority investment in Luckin Coffee in a transaction valued at about $1 billion, giving Abu Dhabi’s sovereign investor exposure to one of China’s largest coffee businesses six years after an accounting scandal forced the company off Nasdaq. Mubadala is investing alongside Centurium Capital, Luckin’s controlling shareholder, and will have the right to nominate a director to the coffee chain’s board.
The investment is significant because Luckin is no longer the company that collapsed in 2020. Founded in 2017, the chain expanded rapidly through low prices, mobile ordering, and an aggressive store-opening strategy. In 2020, Luckin disclosed that employees had fabricated roughly $300 million in sales. The U.S. Securities and Exchange Commission later charged the company with materially misstating revenue, expenses, and its operating loss. Luckin agreed to pay a $180 million penalty, while its American depositary shares were delisted from Nasdaq in July 2020.
The recovery since then has been substantial. Luckin generated RMB15.9 billion, or roughly $2.3 billion, in revenue in the second quarter of 2026, up 28.5% from a year earlier. GAAP operating income increased 22% to RMB2.1 billion, while average monthly transacting customers reached 112.7 million. By the end of June, the company had 36,310 stores, including both self-operated and partnership outlets.
Those figures help explain why Mubadala is interested, but they also show the scale of the challenge. Luckin has grown into a huge retail network in a market where companies compete heavily on price, promotions, and product launches. Its current business model relies on technology, digital customer engagement, and rapid product development, areas Mubadala specifically highlighted when explaining the investment. The sovereign fund said it continues to see long-term opportunities in China’s consumer sector and views Luckin as a technology-enabled business with data embedded across customer engagement, product development, and store operations.
That makes the investment less about coffee as a product and more about the consumer platform Luckin has built around it. A network of more than 36,000 stores and a monthly customer base exceeding 100 million gives Luckin a large distribution system through which it can introduce new drinks, use its digital channels to drive purchases and respond quickly to changes in consumer demand. For Mubadala, acquiring exposure to that platform is a way to participate in China’s consumer economy without having to build a comparable network itself.
The deal also fits Mubadala’s existing China strategy. The sovereign investor says it has invested more than $20 billion in China since 2015, and its presence in the country has expanded beyond individual transactions into a broader portfolio. The Luckin investment, therefore, adds a major consumer business to an investment relationship that Mubadala has been developing for more than a decade.
Also Read:
The structure of the transaction is equally important. Reuters reported that the newly created investment vehicle will hold 241 million Luckin shares, representing a 9.3% economic interest in the company. The purchase is being financed through bank loans secured against the shares, while Mubadala will have the right to appoint a board member. The filing did not disclose how much equity Mubadala itself is putting into the vehicle or how the economic interest is divided between Mubadala and Centurium.
That means the $1 billion headline value should not be interpreted as Mubadala simply writing a $1 billion cheque for a 9.3% stake. The financing structure allows the investors to obtain the economic interest through a leveraged vehicle while Centurium retains its control. Reuters reported that Centurium holds about 48% of Luckin’s voting rights through its super-voting shares, meaning Mubadala is entering the company as a strategic minority investor rather than challenging the existing control structure.
Centurium’s role is important to the investment case because the private equity firm has been closely involved in Luckin’s post-scandal recovery. It first invested in the company in 2018 and eventually took control in 2022 after the Nasdaq delisting and restructuring. Mubadala is, therefore, partnering with an investor that already knows the business and has overseen much of its transformation rather than backing an untested turnaround.
There are still clear risks. Luckin operates in an intensely competitive Chinese beverage market, and its rapid expansion has to be matched by sufficient customer demand and store-level economics. The company also faces the challenge of expanding internationally without allowing overseas growth to become a significant drag on the business. Most of its stores remain in China, although the company has expanded into markets, including Singapore, Malaysia, and the United States.
The accounting scandal can also not simply be separated from the investment. Luckin’s recovery has demonstrated that a company can rebuild after a major governance failure, but Mubadala is now investing in a business whose credibility once collapsed because investors were given materially false financial information. The difference today is that the company has operated for several years under a new ownership and governance structure and has produced substantial revenue and operating income on a scale far beyond its pre-scandal business.
For Mubadala, the attraction is, therefore, the combination of scale, technology, and access to Chinese consumers. Luckin has already built the physical and digital infrastructure that a new entrant would need years to replicate, while its financial performance shows that the post-scandal business is capable of generating billions of dollars in quarterly revenue. The question for the new investors is whether Luckin can maintain that growth while protecting margins and customer loyalty as competition becomes harder.
The investment also gives Abu Dhabi another route into China’s consumer economy at a time when Mubadala is continuing to deepen its presence there. Luckin is a very different investment from the strategic technology and industrial businesses that have attracted much of the attention around China, but that may be part of its appeal: the underlying asset is ultimately tied to everyday consumer spending rather than a highly sensitive technology sector.
Luckin’s story has therefore moved from rapid expansion to corporate scandal to restructuring and now to another phase of institutional investment. Mubadala is not betting on the company that fabricated sales in 2020. It is betting on the business that emerged afterwards, with 36,310 stores, more than 112 million monthly transacting customers, and RMB15.9 billion in quarterly revenue. Whether that transformation can translate into durable returns is now the central question behind Abu Dhabi’s decision to take a stake. Whether that transformation can translate into durable returns is now the central question for Mubadala as it takes a stake in Luckin.