Rising Bond Yields Add Billions to G7 Borrowing Costs as Debt Pressure Builds
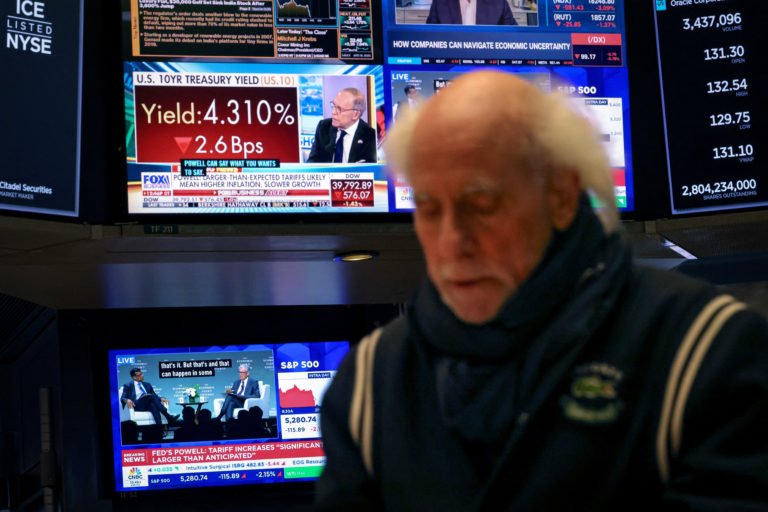
A trader works, as a screen broadcasts a live interview with U.S. Federal Reserve Chair Jerome Powell, on the floor at the New York Stock Exchange (NYSE) in New York City, U.S., April 16, 2025. REUTERS/Brendan McDermid
Rising Bond Yields Add Billions to G7 Borrowing Costs as Debt Pressure Builds
Higher government bond yields are becoming an increasingly expensive problem for the world’s richest economies, with rising borrowing costs already adding billions of dollars to the amount governments will have to spend servicing their debt.
G7 countries have taken on an estimated additional $16 billion in sovereign debt-financing costs as bond yields have risen since the U.S.-Iran war began in February, according to an analysis published by the Financial Times on Sunday
If yields stay around current levels, the additional cost could rise by another $34 billion by the first quarter of 2027, the analysis found. The United States faces the biggest increase, with an estimated $10.6 billion already added to its financing bill and a potential further $21.7 billion if elevated yields persist.
The numbers matter because governments are entering this period with large debt loads and substantial financing requirements. Higher rates do not immediately reprice the entire stock of outstanding debt, but they gradually raise the cost as old bonds mature and are replaced with new ones.
That process can put pressure on budgets for years.
Why Bond Yields Have Moved Higher
The recent increase in yields has not been driven by one factor.
Investors have been dealing with higher inflation risks, heavy government borrowing, geopolitical uncertainty, and expectations that interest rates could remain higher for longer.
The conflict involving the United States and Iran has added to those concerns, particularly through energy markets. Higher oil prices can feed directly into inflation, making it harder for central banks to ease monetary policy.
There is also a supply issue.
Governments need to issue large quantities of debt to finance existing obligations and new spending. At the same time, private investment demand has increased in areas such as artificial intelligence, while governments are spending more on defence and infrastructure.
That leaves bond investors demanding greater compensation in some markets to absorb the additional supply and risk.
Reuters reported earlier this month that long-term borrowing costs across the United States, Germany, and Japan had reached multi-year or multi-decade highs as investors reassessed inflation, government debt, and geopolitical risks.
The U.S. Treasury Market Is at the Centre of the Problem
The United States has the largest government bond market in the world, making movements in Treasury yield important well beyond Washington.
The 30-year Treasury yield briefly reached 5.337% on August 18, its highest level since 2007, according to Reuters. It subsequently eased after the U.S. Treasury announced that it would double the size of its liquidity-support operations for longer-dated bonds.
Even so, the underlying pressure has not disappeared.
The U.S. government must continually refinance maturing debt while issuing new securities to cover its fiscal needs. When market yields are higher, newly issued debt becomes more expensive.
The effect builds over time rather than appearing all at once.
For example, a Treasury bond issued several years ago at a lower interest rate does not suddenly become more expensive because market yields have risen. The government continues paying the rate agreed when the bond was issued. The additional expense comes when that debt matures and has to be replaced at prevailing market rates.
With such a large amount of U.S. debt outstanding, even relatively small changes in borrowing costs can eventually translate into substantial sums.
Europe Is Feeling the Same Pressure
The United States is not alone.
European governments are also bringing large amounts of debt to the market while investors demand higher returns.
Germany and other euro-zone governments have increased bond issuance, adding to pressure in European debt markets. Reuters reported last week that record German debt sales were contributing to strains across the region, with long-term borrowing costs elevated.
The rise in yields also reflects changing expectations about European monetary policy.
If inflation remains stubborn, investors may expect central banks to keep rates higher for longer. That pushes up the return they demand on longer-dated government securities.
For heavily indebted governments, the combination of high debt and higher refinancing costs can become uncomfortable even without a sudden financial crisis.
Japan Has Its Own Bond-Market Problem
Japan is another important part of the global picture.
Japanese government bond yields have climbed as investors have become more concerned about inflation and the country’s fiscal position. Reuters reported on August 18 that Japan’s benchmark 10-year yield was approaching 3%, a level not seen since the mid-1990s.
Japan’s debt market matters globally because Japanese investors hold large amounts of overseas assets. Changes in domestic yields can influence whether money remains invested abroad or returns to Japan.
That is one reason movements in Japanese government bonds and the yen are being watched closely by international investors.
The Fed Has Added Another Layer of Uncertainty
The U.S. Federal Reserve is now facing a particularly difficult policy environment.
At the Jackson Hole economic symposium on Friday, Fed Chair Kevin Warsh said the central bank would have “work to do” if policymakers failed to gain sufficient confidence that underlying inflation was moving back toward its 2% target.
His comments increased market expectations for a possible rate increase at the Fed’s September meeting. Reuters reported that traders shifted toward expecting tighter policy following the speech.
That matters for bond investors because expectations about future Fed policy influence treasury yields across the maturity curve.
If investors believe rates will remain elevated, they generally demand higher yields on longer-term government debt.
The result can be a feedback loop: stronger inflation concerns push rate expectations higher, higher expected rates support higher bond yields, and higher yields increase the cost of financing government and private-sector borrowing.
What It Means for Companies and Households
The pressure does not stop with government finances.
Government bonds are a benchmark for pricing many other forms of borrowing. When Treasury and other major sovereign yields rise, corporate borrowers may have to offer higher interest rates to attract investors.
Companies that depend heavily on debt and therefore face greater financing costs.
Households can also feel the effect through mortgages and other forms of credit, although the impact varies between countries and loan products.
Higher borrowing costs can eventually weigh on investment, construction, and consumer spending.
That is why bond-market movements can become an economic story rather than remaining an issue for professional investors.
Stocks Are Also Vulnerable
Equity markets have another reason to pay attention.
When government bond yields rise, investors can obtain a higher return from relatively safer assets. That can reduce the premium investors who are willing to pay for stocks, particularly companies whose valuations depend heavily on profits expected many years in the future.
Technology and other growth stocks can be especially sensitive because a larger portion of their valuation is based on future earnings.
Reuters reported on August 18 that major stock markets, including the Nasdaq and Europe’s STOXX 600, came under pressure as long-term borrowing costs climbed.
This does not mean higher yields automatically trigger a stock-market sell-off. But sustained increases can change how investors value risk across financial markets.
The Bigger Question Is How Long Yields Stay High
The immediate increase in government financing costs is significant, but the bigger concern is duration.
A short-lived jump in yields can be absorbed as governments refinance debt over time. A prolonged period of elevated rates is more difficult.
The FT’s analysis estimates that the G7 could face another $34 billion in financing costs by the first quarter of 2027 if current yield levels persist.
That does not mean governments will suddenly need to find an additional $34 billion in cash. The figure represents the estimated additional financing burden associated with the higher yields.
Whether that burden becomes larger or fades will depend heavily on inflation, energy prices, economic growth, central-bank decisions, and investor demand for government debt.
Those variables are now closely connected.
What Investors Should Watch Next
The next few months could provide a clearer indication of whether the recent bond-market pressure is temporary or part of a longer shift.
Oil prices will remain important because another sustained rise in energy costs could keep inflation expectations elevated.
The Federal Reserve will also be central. Any indication that policymakers are prepared to raise rates again could push Treasury yields higher.
Government borrowing plans will matter as well. Large debt issuance at a time when investors are already demanding higher returns could put additional pressure on bond markets.
Japan and Europe deserve attention for similar reasons, particularly as their governments manage large financing needs alongside changing monetary-policy expectations.
For investors, the key signal is not simply whether yields rise or fall on a particular trading day. It is whether the market begins to accept a world in which government borrowing costs remain structurally higher than they were during the years of ultra-low interest rates.
Makon Financials Conclusion
The latest increase in G7 borrowing costs is a reminder that higher interest rates can take time to show their full effect.
Governments are not refinancing every bond at once. Instead, the cost builds as old securities mature, and new debt is issued at higher rates.
That makes the current bond-market move important even if there is no immediate fiscal crisis.
The combination of large government debt, persistent inflation risks, heavy bond issuance, and geopolitical uncertainty has created a more demanding environment for borrowers.
For investors, government bonds are therefore becoming one of the clearest places to watch the direction of the global economy.
If yields remain elevated into 2027, the consequences could extend beyond government budgets, affecting corporate financing, household credit, equity valuations, and the decisions of central banks around the world.
Source; Financial Times